
How do buyers value a sleep laboratory: A Process Explainer

How to value a medical practice is not a question answered by one industry multiple. For a sleep laboratory, buyers examine the durability of earnings, the condition and utilization of equipment, clinical and referral operations, compliance exposure, and how well the business can run after the owner exits. The goal is to understand both what the business earns today and how much risk or investment comes with transferring that performance.
What does a buyer mean by value?
A buyer’s view of value is an investment judgment, not simply a calculation applied to revenue. The same reported earnings can support different conclusions depending on whether they are recurring, documented, and likely to continue under new ownership. Buyers also weigh the resources required to maintain the business and the risks they would assume.
For a sleep laboratory, this means separating the operating business from individual assets. Beds, monitoring systems, software, and other equipment matter, but their purchase price or book value does not establish the value of the whole company. Buyers ask whether the equipment is serviceable, appropriately deployed, and capable of supporting reliable operations. They also consider whether replacement or upgrades may be needed.
The IRS discussion of medical-practice valuation describes an income approach as one method for considering a practice’s economic performance, while also addressing allocation of business value. It is useful background, not a substitute for transaction-specific analysis: IRS guidance on valuation of medical practices.
In practice, buyers usually triangulate rather than rely on one calculation. They may compare the income the company can sustain with the assets and operating capabilities required to produce it. They then test the result against the business’s risk profile and the terms under which a transaction could be completed. A well-supported valuation discussion makes the assumptions visible: what performance is included, what liabilities or investment needs are excluded, and what must remain in place after a change of control.
How do earnings and revenue quality affect valuation?
Buyers typically start with financial records and ask what earnings the business can reasonably sustain. Revenue alone can conceal important differences. A laboratory with stable utilization and documented collections may present a different risk profile from one with volatile volume, unresolved denials, or dependence on a small number of referral relationships.
Owners should be ready to explain the path from patient activity to collected revenue. That includes how services are billed, how collections are tracked, and which costs are required to produce the results. If the owner has personal expenses or one-time items in the financial statements, they should be clearly documented rather than assumed to be adjustments.
- Consistency:
Can monthly and annual results be reconciled to source records?
- Collection quality:
Are billed services converted to cash in a clear, trackable way?
- Customer and referral concentration:
Does volume rely heavily on a narrow group of sources?
- Expense normalization:
Are proposed adjustments supported by records and tied to genuine nonrecurring or owner-specific costs?
- Working capital needs:
What cash, receivables, and operating resources are needed to keep the laboratory running?
A buyer may challenge an adjustment that is not supported or that represents a real ongoing cost. Sellers should avoid presenting an optimistic earnings figure without a clear bridge from reported results. Well-organized records help both sides focus on the economic substance rather than debating basic data.
It helps to build a simple monthly bridge from completed studies to billed services, adjustments, cash collections, and outstanding receivables. The bridge should use consistent definitions and explain timing differences. If a period shows a sudden change, identify whether it reflects volume, payer mix, billing practices, staffing, or a one-time event. This level of detail lets a buyer distinguish an operational trend from a reporting artifact.
Which operating factors can change a buyer’s view?
Financial performance is only part of the analysis. A sleep laboratory depends on clinical workflows, skilled staff, equipment, scheduling, and relationships that support patient volume. Buyers consider how these pieces fit together and whether they can continue without the founder’s constant involvement.
Useful questions include: Who manages daily operations? How are staff trained and scheduled? How are patient records and operational data maintained? What happens when a key clinician or referral relationship changes? Is the facility and equipment configured to support current services? These questions help buyers identify continuity strengths as well as gaps.
Regulatory, credentialing, payer, and privacy requirements also deserve careful review. The specific requirements depend on the laboratory’s services, location, contracts, and operating model. Owners should organize applicable licenses, accreditations, policies, payer documents, and compliance records, and consult qualified legal and regulatory professionals about issues specific to their business.
Continuity is especially important when the founder performs several roles at once. A buyer may want to understand which decisions are clinical, managerial, financial, or relationship-based, and who is prepared to assume each responsibility. A practical succession map can identify key-person dependencies without overstating that every role can be replaced immediately. Written processes, clear reporting lines, and staff cross-training can make the transition easier to evaluate.
How do buyers assess equipment and capacity?
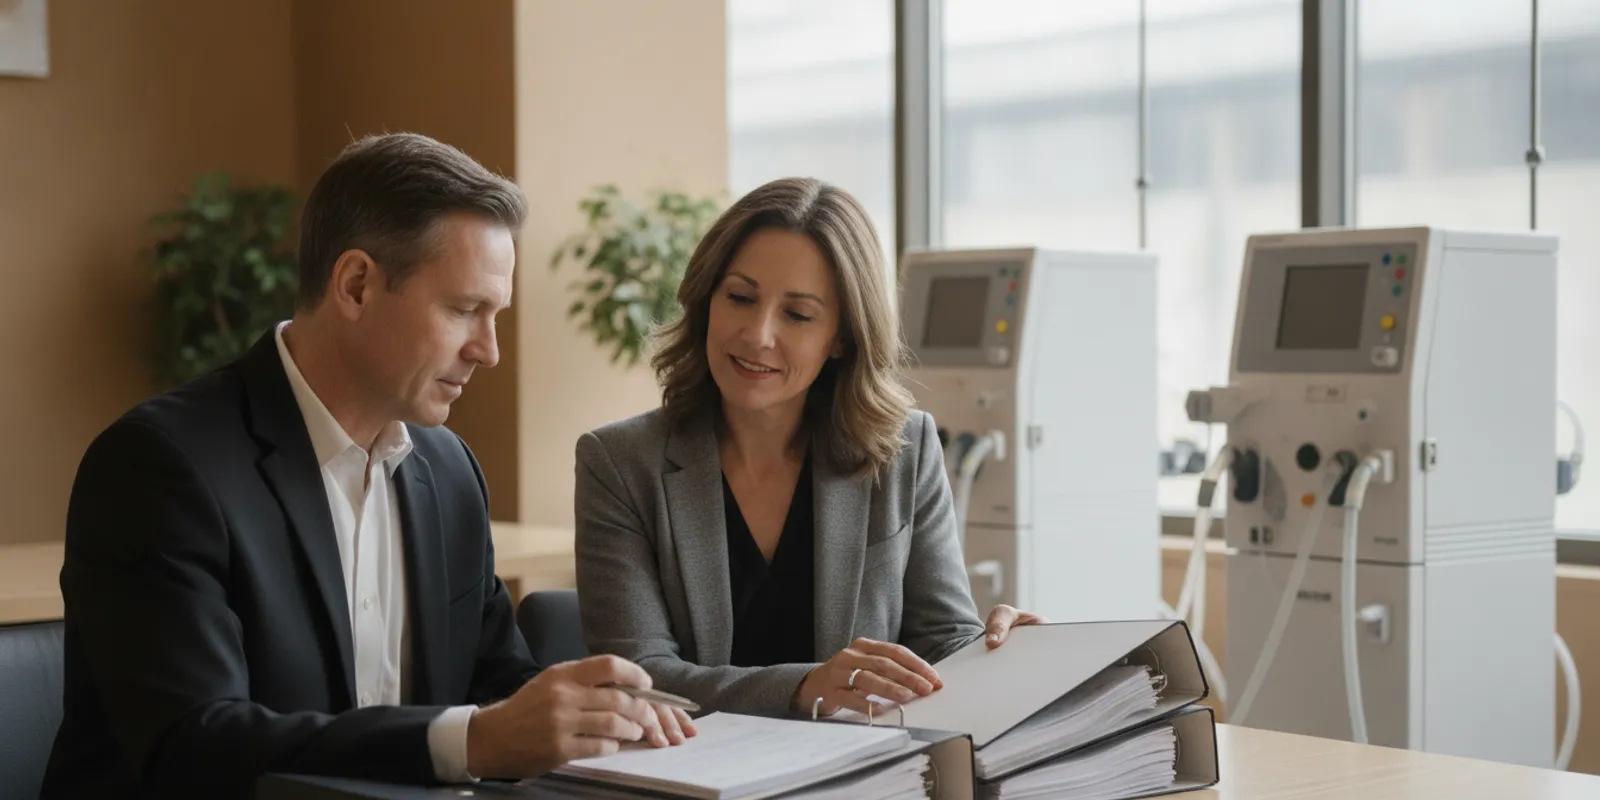
Equipment can support a laboratory’s ability to deliver services, but buyers look beyond an asset list. They may examine age, condition, maintenance history, replacement plans, utilization, and whether the equipment is owned, leased, or subject to other obligations. They also consider whether capacity is aligned with actual demand and staffing.
Area | What the buyer may examine | What the owner can prepare |
Diagnostic equipment | Condition, service records, age, utilization, and replacement needs | Asset register, invoices, maintenance logs, and lease documents |
Facility and capacity | Room availability, scheduling constraints, and operational fit | Facility agreements, capacity overview, and utilization records |
Clinical operations | Staffing coverage, documented workflows, and continuity | Role descriptions, training records, policies, and process maps |
Revenue performance | Collections, payer and referral patterns, and earnings consistency | Reconciled financial statements and supporting reports |
Capacity should be described carefully. The existence of unused rooms or equipment does not automatically mean that a buyer can convert it into profitable growth. A buyer may ask what staffing, demand, approvals, or investment would be needed to use that capacity. A credible explanation distinguishes proven performance from a future opportunity.
Owners can make the equipment story more useful by connecting assets to actual operations. For each major item, record its role in the service workflow, operational condition, maintenance history, ownership status, and any known constraints. Explain whether a backup is available and whether downtime has affected scheduling. Avoid describing equipment as a growth asset unless there is a documented path to use it, including the personnel and other resources required.
How are buyer and seller perspectives different?
Sellers often focus on the work they have invested and the growth they believe is possible. Buyers focus on what can be substantiated, transferred, and funded after closing. These perspectives are not incompatible, but they need to be reconciled with evidence.
Seller perspective | Buyer question | Practical response |
“We have strong referral relationships.” | Are the relationships institutional or tied to the owner? | Document sources, history, agreements, and transition dependencies. |
“There is room to grow.” | What must change to realize that growth? | Separate current results from a supported operating plan. |
“The equipment is valuable.” | Will it remain useful, and what investment is due? | Provide condition, maintenance, ownership, and replacement details. |
“The business can operate without me.” | Which decisions and relationships still depend on the founder? | Map responsibilities and create practical continuity documentation. |
This is where preparation can influence the quality of the discussion. The objective is not to eliminate every risk. It is to identify material issues early, explain them accurately, and show how the business operates beyond the founder’s personal knowledge.
Seller optimism can be useful when it points to an opportunity, but it should not be confused with an achieved result. A buyer may give more weight to an established referral pattern than to an informal expectation of additional referrals. Likewise, a plan to extend hours or add capacity is more meaningful when it identifies responsible staff, operational costs, and a credible source of demand. Clear distinctions protect the seller’s credibility and help the parties discuss upside without presenting it as guaranteed.
How should an owner prepare for a valuation discussion?
A useful preparation effort creates a coherent picture of the business instead of a pile of files. The P.R.I.M.E. exit-planning method emphasizes building and de-risking a company before an exit. Applied to a sleep laboratory, that means making performance understandable, reducing avoidable owner dependence, and clarifying what a buyer would need to continue operations.
- Reconcile financial records.
Assemble financial statements, tax records, and supporting schedules. Explain unusual changes and document any proposed adjustments.
- Map the operating model.
Show how patients move through scheduling, testing, interpretation, billing, and follow-up. Identify the roles that keep each step working.
- Inventory assets and obligations.
List equipment, ownership or lease status, maintenance history, facility commitments, and known replacement needs.
- Organize contracts and compliance materials.
Gather relevant payer, vendor, referral, employment, licensing, accreditation, and policy records, while protecting sensitive information.
- Test founder dependence.
Identify decisions, relationships, and expertise held primarily by the owner. Create a transition plan where practical.
- Separate fact from forecast.
Present current results distinctly from projections, expansion ideas, or uncommitted opportunities.
Consider preparing a short operating narrative alongside the records. It can explain the service mix, normal scheduling cadence, staffing model, key revenue drivers, and known constraints. The narrative is not a substitute for source documents; it helps a reviewer know how the documents fit together and where to ask follow-up questions. A consistent index also makes it easier to update information as circumstances change.
Owners who want to understand how a formal transaction process is organized can review PRIME exits’ exit planning and coaching resources and its M&A video gallery. For healthcare-sector context, explore the firm’s healthcare M&A advisory information and reports and resources.
Use secure, access-controlled methods for sensitive material, and avoid distributing patient-identifiable records during early discussions. A qualified advisor and the appropriate legal professionals can help determine what information is needed, when it should be shared, and how to protect confidentiality. This is a practical readiness consideration, not a substitute for advice tailored to the laboratory’s privacy obligations.
Why is a single multiple not enough?
A market multiple can be a reference point, but it cannot answer every question about a particular laboratory. Comparisons may differ in size, service mix, geography, earnings quality, payer exposure, equipment needs, and transaction structure. A headline multiple detached from those facts can create false precision.
Value may also be discussed in different ways: enterprise value, equity proceeds, cash at closing, or total consideration that includes contingent or deferred components. Those figures are not interchangeable. Owners should understand what liabilities, working capital, transaction expenses, and deal terms do to the proceeds they may ultimately receive.
For example, two laboratories might report similar earnings, yet differ in the equipment replacement expected soon, the owner’s role in daily operations, or the stability of referral sources. The difference is not captured by a single number without examining the assumptions behind it. A useful discussion asks what the proposed figure includes, which obligations remain with the seller, and how the structure affects proceeds. This is why owners should evaluate the complete transaction economics rather than fixating on a headline value alone.
The strongest analysis combines financial performance with operational diligence and buyer context. PRIME exits represents founder-led businesses in healthcare and other sectors, and healthcare transactions are conducted through American Healthcare Capital and affiliated partners, subject to applicable requirements. Learn about the M&A advisory team and the firm’s closed transaction experience.
That broader perspective also helps an owner preserve options. A business may attract interest from different kinds of buyers, and each may assess strategic fit, operating continuity, and investment needs differently. The valuation conversation should therefore clarify what the company can support and what the owner hopes to achieve, rather than assume that one multiple or one buyer profile will define the outcome.
Frequently Asked Questions
Can I estimate a sleep laboratory’s value from revenue?
Revenue can provide context, but it does not show the costs, collections, investment needs, or risks associated with producing that revenue. A buyer will want to understand sustainable earnings and the operating conditions behind them.
Does equipment value determine the sale price?
No. Equipment is one part of the business. Condition, utilization, ownership, maintenance, and future replacement needs matter, along with earnings, staff, contracts, operations, and transferability.
Will projected growth increase value?
Potential growth may inform a buyer’s view, but forecasts are stronger when supported by specific evidence and a credible plan. Keep projections distinct from historical results and explain what resources or approvals growth would require.
When should an owner begin preparing?
Preparation is most useful before a sale process is imminent, because documentation and operating improvements can take time. An owner can begin by reconciling financial information, organizing key records, and identifying where business knowledge remains concentrated.
For owners who want a structured way to build a business buyers can understand and compete for, the PRIME exits Business Exit Readiness Course covers practical exit-readiness principles. Begin building a more buyer-ready company with the course.
Comments